Why Was My Claim Denied? What to Check Next
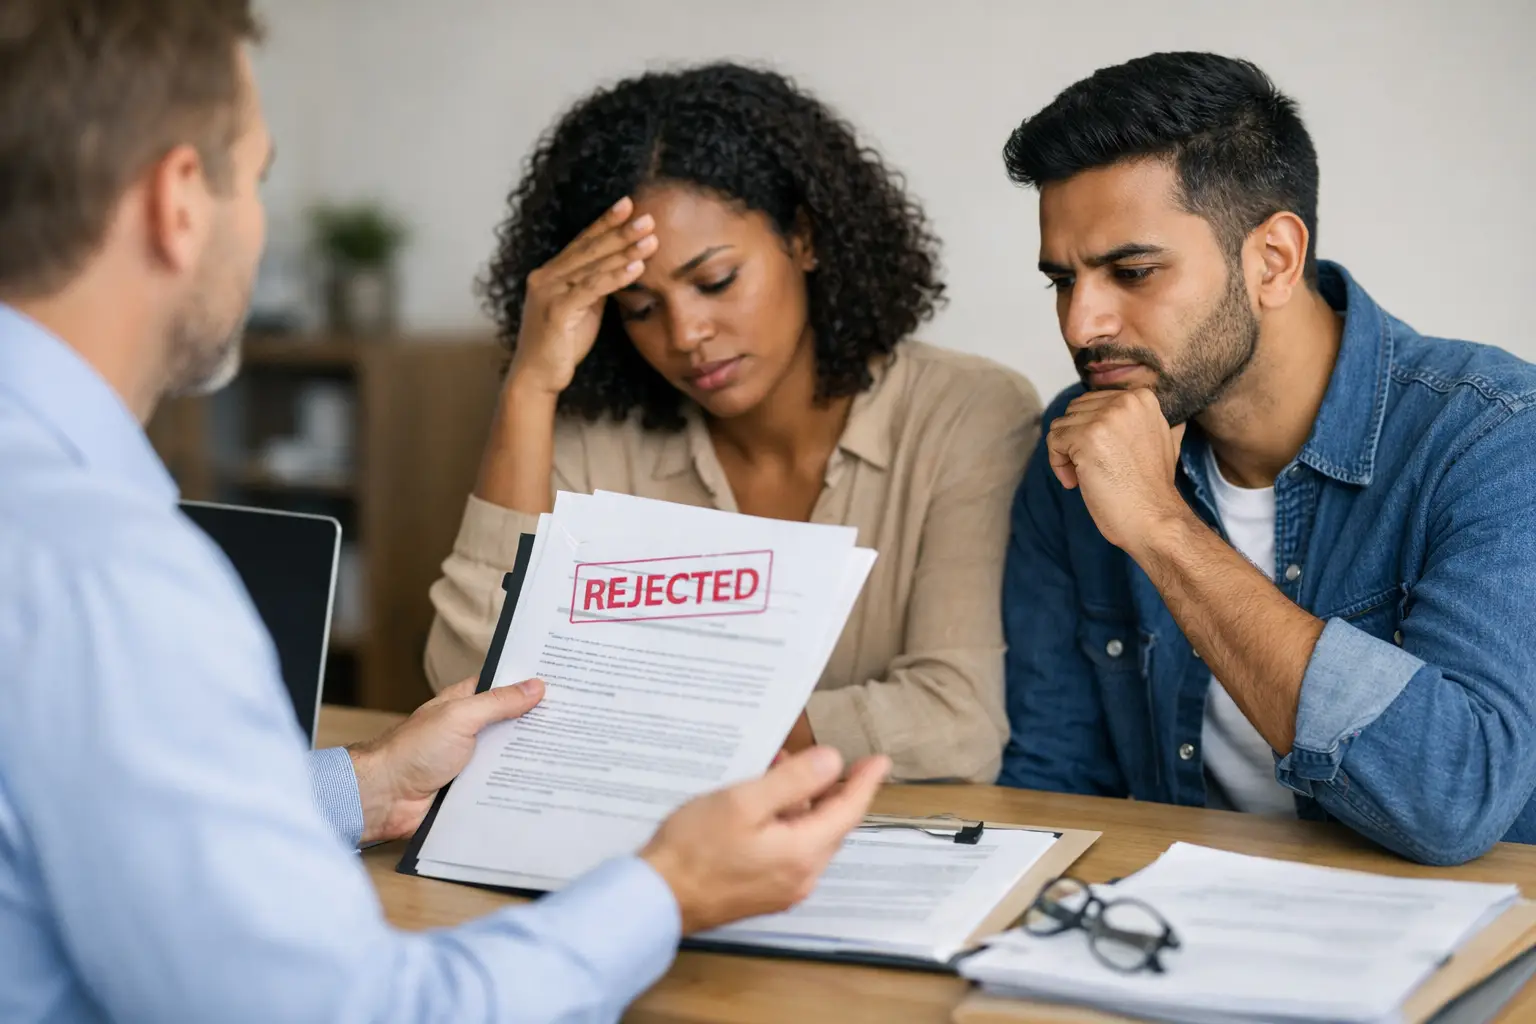
A denied claim can arrive weeks after an appointment, test, or prescription was filled, often with little more than a short code and a frustrating balance. If you are asking, “why was my claim denied,” start by separating the insurer’s decision from the bill itself. A denial may be correctable. It may also mean the service was processed under a benefit rule you did not know applied.
The fastest path forward is to identify exactly what was denied, why the plan says it was denied, and whether the provider has already been asked to correct or resubmit the claim. You do not need to become an insurance expert. You do need the right documents and a clear sequence of questions.
Why Was My Claim Denied? Start With the EOB
For most medical services, your Explanation of Benefits, or EOB, is the place to begin. It is not a bill. It is the health plan’s record of how it processed the claim submitted by your doctor, hospital, lab, therapist, or other provider.
Find the date of service, provider name, billed amount, plan-paid amount, and patient responsibility. Then look for the denial reason or adjustment code. The wording may be plain, such as “prior authorization required,” or it may direct you to a code explanation elsewhere on the EOB or your member portal.
Pharmacy claims work somewhat differently. A prescription may be rejected at the pharmacy counter before a claim is paid, or a pharmacy benefit manager may send a notice afterward. The reason could involve the drug’s formulary status, quantity limits, step therapy, prior authorization, refill timing, or the pharmacy’s network status. Save the rejection message, receipt, and any notice from your pharmacy benefit plan.
A denial is also different from a claim that is still pending. If the EOB says the claim needs more information or is under review, ask the insurer what is missing and who must provide it. A provider may need to submit clinical notes, an operative report, a referral, or a corrected claim.
The Most Common Reasons Claims Are Denied
Denial notices can sound final, but the underlying reason often falls into a limited set of categories. Understanding the category helps you choose the next action instead of making a general call to customer service without the details.
The service needed prior authorization
Many plans require approval before certain imaging studies, surgeries, therapies, specialty medications, or higher-cost procedures. If authorization was not obtained, obtained after the service, or approved for a different location or date range, the claim may deny.
This does not automatically mean you owe the full amount. Ask whether the provider submitted an authorization request, whether a reference number exists, and whether the authorization covered the specific CPT or procedure code billed. If the provider believed no authorization was required, request that they verify the plan’s rule and consider a corrected submission or retrospective review if available.
The plan found the service was not medically necessary
“Not medically necessary” does not mean the service was useless or that your clinician made a poor recommendation. It means the plan determined that the submitted documentation did not meet its coverage criteria for that service in that situation.
Medical policies may require a diagnosis, documented symptoms, prior conservative treatment, lab results, imaging findings, or a particular treatment sequence. Ask for the exact policy or clinical guideline used in the decision and the criteria the plan says were not met. Your clinician can then determine whether additional documentation, a peer-to-peer review, or an appeal is appropriate.
The provider, facility, or pharmacy was out of network
Network status can be more complicated than it appears. Your surgeon may be in network while the facility, anesthesiologist, laboratory, radiologist, or durable medical equipment supplier is not. For prescriptions, the medication may be covered but the dispensing pharmacy may not participate in your pharmacy network.
Emergency care and certain surprise-billing protections can change what you owe, depending on the circumstances and your plan. Still, do not assume a network-related denial is protected or unprotected without checking the EOB, your benefit documents, and the plan directly.
The claim was coded, billed, or filed incorrectly
Claims rely on administrative details: CPT or HCPCS procedure codes, diagnosis codes, modifiers, place-of-service codes, dates, provider identifiers, and coordination-of-benefits information. A small mismatch can trigger a denial.
For example, a service may have been billed under a code that does not match the approved authorization, paired with an incomplete diagnosis code, or submitted to the wrong insurer. In these cases, the provider’s billing office usually needs to act. Ask for an itemized bill and confirm the service date, provider, code, and insurer information are accurate.
The benefit has limits or the service is excluded
Some services are excluded from a specific plan, limited to a set number of visits, covered only after a deductible is met, or available only through designated providers. A plan might cover physical therapy but limit visits, cover a lab test only under certain conditions, or cover a medication only after preferred alternatives have been tried.
A deductible is not technically a denial. If your EOB says you owe the amount because your deductible has not been met, the claim may have processed as covered but paid zero dollars. That distinction matters because an appeal may not change a valid deductible obligation, while a true coverage denial may warrant further review.
What to Do After a Claim Denial
Act before the appeal deadline printed on the EOB or denial letter. Plans often set separate deadlines for provider claim corrections and member appeals, so waiting for one party to act can create problems.
First, call the member-services number on your insurance card and ask focused questions. Request the denial reason in plain language, the exact code or policy used, whether the claim can be reconsidered, and the deadline for an internal appeal. Write down the representative’s name, the call date, and any reference number.
Next, contact the provider’s billing office. Share the denial reason and ask whether it was a coding, filing, authorization, or documentation issue. Providers can often correct factual errors, submit missing records, or resubmit a claim. If the denial is based on medical necessity, ask whether the clinician can review the insurer’s criteria and provide supporting documentation.
Keep a simple claim file with the EOB, denial letter, itemized bill, authorization records, referral, relevant clinical notes, call log, and copies of every form submitted. This record is useful if the issue moves from a correction request to a formal appeal.
If you appeal, address the plan’s stated reason rather than only describing how upsetting the result has been. A strong appeal identifies the service, date, claim number, and denial rationale, then includes documents that respond to the missing requirement. Your plan’s appeal instructions should explain where to send it and whether an expedited review is available when a delay could seriously affect your health.
Verify Coverage Before the Next Service
A denied claim is also a practical signal to check future services before they occur. Ask the ordering clinician for the procedure name and, when available, the CPT or HCPCS code. For medications, ask for the drug name, strength, route, and expected quantity. These details let you ask your plan a precise question instead of asking whether something is “covered” in general.
Then confirm four points: whether the service is a covered benefit, whether prior authorization or a referral is required, whether the provider and facility are in network, and which medical policy or pharmacy rule applies. Coverage can depend on your state, plan type, network, diagnosis, and documentation, so a general internet answer is not a coverage guarantee.
AuraCode can help you understand a procedure or code in plain language and locate insurer-specific policy and authorization information. Use that information to prepare for a conversation with your plan and care team, not as a substitute for the plan’s final determination.
A claim denial is paperwork with real financial consequences, but it is not always the end of the process. Read the reason, verify the facts, involve the right party, and respond within the deadline. The more specific your questions become, the easier it is to move from an unexplained “no” to the next workable step.